Mortgage company holding the insurance check? See how long lenders can hold it, how loss draft departments release funds, and how contractors get paid.


You know the feeling. You have just knocked out an incredible restoration project. Your team went above and beyond, the homeowner is thrilled, and your reputation is solid. There is just one issue: the payment is AWOL, because the mortgage company is holding the insurance check. If you have ever had a mortgage company holding an insurance check for repairs you already finished, you know how long that money can sit in a loss draft department.
If you are in the restoration business, you know exactly what that means. Mortgage companies decide when and how you get paid, and it is never on your schedule. They are not in a rush.
It is frustrating, but you are not powerless. Instead of reacting, turn the nonnegotiables of working with mortgage companies into part of your business systems. Build their inspections, staged releases and paperwork into how you plan, price and document every job, and you get a business with steadier cash flow and a lot less stress. This guide shows you how.
KEY TAKEAWAYS
Let's get this straight: mortgage companies are not your enemy. They are involved because they have to protect their own investment in the property.
Their involvement does add layers of complexity and extra days to your payment timeline. They are also the real moneybags and property owners behind the project. Once you understand both their necessity and their limitations, you can shift the game, take control and get paid.
Three facts of life come with every mortgage company job:
| 1 | Dual ownership The check is made out to the homeowner and the mortgage company, and the lender often sends inspectors to verify the work. |
| 2 | Check disbursement timelines Funds are released in stages as milestones and inspections are completed. |
| 3 | Dual endorsement The check needs two signatures before it can be cashed or deposited. |
Here is what each one means and how to keep it from stalling a project again.
This is the question every restoration owner asks first, and the honest answer is that there is no single national deadline. How long a mortgage company can hold an insurance check depends on who owns or insures the loan, whether the loan is current, the size of the claim, and the law in the state where the property sits.
A few facts are worth knowing before you set expectations with a homeowner:
Tip: On the first call with the homeowner, ask who services the loan and get the loss draft department phone number. Ask the homeowner to request the lender's release requirements and expected timeline in writing, and to add you as an authorized contact if the lender allows it.
The rest of this guide is about the part you can control: how fast your paperwork, inspections and follow-up move each stage of that timeline.
Most lenders run insurance checks through a loss draft department (sometimes called an insurance claims or property loss department). The names change from lender to lender, but the sequence on a typical restoration or roofing claim looks like this:
| 1 | The carrier issues a two-party check The insurance claim check names the homeowner and the mortgage company (and sometimes the contractor). Nobody can deposit it alone. |
| 2 | The homeowner contacts the loss draft department The lender opens a claim file and sends its requirements: usually a claim packet, the adjuster's estimate and a signed contractor agreement. |
| 3 | The homeowner endorses and mails the check The lender endorses it and either returns it or deposits it into a loss draft account. |
| 4 | An initial draw is released Often enough to start the job, tied to the signed contract and approved estimate. |
| 5 | Loss draft inspections trigger later draws The homeowner or contractor requests an inspection at each milestone. A passed inspection releases the next payment. |
| 6 | Final inspection and final release The last draw usually needs a completion certificate, a final invoice and, on many files, a lien waiver. |
Every lender has its own packet, but these items show up on almost every file. Build them into your job checklist so they exist before anyone asks.
| Document | Who provides it | When it is needed |
|---|---|---|
| Endorsed insurance check | Homeowner | Start of the file |
| Adjuster's estimate or claim settlement | Homeowner (from the carrier) | Start of the file |
| Signed contract with scope and price | Contractor and homeowner | Before the initial draw |
| Contractor W-9, license and proof of insurance | Contractor | Before the initial draw |
| Progress photos and progress invoice | Contractor | Each inspection |
| Completion certificate and final invoice | Contractor and homeowner | Final draw |
| Lien waiver for the amount paid | Contractor | Final draw (sometimes each draw) |
The homeowner is the lender's customer, so most of the calls to the loss draft department have to come from them. Your job is to make those calls easy: hand the homeowner a one-page summary with the claim number, loan number, the documents already sent and the next milestone. Our post on getting homeowners and adjusters to agree to pay you covers the authorizations to collect at the start of the job.

When a homeowner files an insurance claim, the insurance company issues a check for the restoration work. Here is the hitch: that check does not go directly to you. It is made out to both the homeowner and the mortgage company. Lenders often call this a loss draft check, and many handle it through a dedicated loss draft department.
That is because the mortgage company has a financial interest in making sure the property is properly restored before releasing the funds. To confirm the work is done to spec, mortgage companies often hire third-party inspectors to verify the quality and progress of your work. In other words, your work has to pass inspection by outside professionals before you get paid.
If they do not approve of what they see, the payment gets delayed. Loss draft inspections are usually scheduled by the lender's vendor, not by you, so a missed appointment can push a draw back by a week or more. When you build your project timeline, account for the time to do the work, the time to schedule the inspection, and a contingency in case you fail the inspection the first time around.
There is no way to get rid of mortgage companies or change their policies around insurance or inspections. You can, however, change how frustrating the project is by changing how you approach the inspection process.
Deliver everything they need before they ask. What often slows inspections down is the inspector asking for documentation you did not expect. The labor is finished, but now you have to find or create the paper trail to get what is rightfully yours. Instead of wasting time after the work is done, prepare your paperwork and inspection materials as you go.
Ask and understand ahead of time. Reach out to the third-party inspector at the start of the process and learn the steps and requirements of their inspection. That saves you delays and speeds up the project.
Tip: Ask the inspector what the common delays are on projects similar to yours in size and scope.
Document like your timeline depends on it. To keep money flowing, you need detailed documentation (photos, invoices, receipts, lien waivers) that proves the work is being done to spec. Collect it as you work so that on inspection day you can sail through and move your payment forward. Our guide to bulletproof documentation covers what to capture.
Tip: Take a photo every day you are on the job site. If you are working, something has changed. Document it.

There is no magic wand that speeds up a project or suddenly drops cash into your account. You can, however, shape how the project is perceived by how you frame it. Do not try to impress the customer with a lower price or an overly aggressive timeline. Be honest and realistic up front. It is more professional and it protects trust across the project.
Build a realistic timeline, not an optimistic one. We all like delivering good news and looking like the fastest crew in town. But when you give a customer a best-case plan and budget, every delay becomes bad news and a ding on your ability to estimate a job.

Build delays into your project timeline. It might feel counterintuitive, but give your customer a worst-case timeline. As things (hopefully) go better than the worst case, your customer keeps being surprised, impressed and happy throughout the job.
Tip: Look at previous jobs of a similar size and scope. Average their timelines, then add a 10% contingency. Use that as the timeline for the project.
Plan for an unbalanced budget. It is great when payments arrive on time. We know they often do not. You have been in this game long enough to know funds will be released in stages, so plan for it. Build a financial cushion into your project budgets, secure a line of credit, or negotiate better payment terms with your suppliers. Make the mortgage company's conditions simply part of the plan.
Meeting other people's expectations and planning for factors outside your control matter. There is also plenty you can control within your own work.
Comply with strict standards by exceeding them. Mortgage companies do not just want repairs. They want partners they can trust, whose work meets strict building codes and industry standards. That is why inspections are the make-or-break step in our industry. If your work falls short, the mortgage company carries the burden and your business suffers. Here is how to exceed expectations:
Make quality assurance a non-issue. Striving for excellence is about more than getting paid. It builds your reputation as a top-tier contractor. When you consistently deliver quality, mortgage companies trust you, and payments flow more smoothly.
Tip: Figure out which past jobs really knocked it out of the park, then share those standards and expectations with your crew so everyone knows what you want to deliver.

Do not get beat on building code compliance. Know your local building codes inside and out. If your work does not meet code, the inspector will flag it, and payment waits until the issue is fixed. Do it right the first time, every time.
Tip: Reach out to your building inspectors and ask what to keep an eye on, what the normal standard is, and what they want to see to pass the inspection easily. Inspectors are people too, and that relationship can pay dividends well beyond one job.
One more secret weapon should run through every step of your process: communication. Make working with you as easy as it can be. Every interaction is a chance to show your professionalism, streamline your operations and build your reputation. Communicating is never an obligation. It is always an opportunity.
Communicate regularly. Keep the mortgage company in the loop from day one. Send updates on project progress, address their concerns promptly, and make sure they know you are on top of things.
Tip: Reach out every 3 to 5 days with a progress report or any outstanding information. When they trust you, they release payments faster.
Understand their processes. Every mortgage company has its own way of doing things. Learn how each one operates so you can anticipate their needs and streamline the payment process.
Tip: Ask what you should know about their process and what mistakes other restoration companies have made. Learn from others' errors.
Bring one overdue invoice.
We'll show you how follow-up on a mortgage company job would run, stage by stage.

Even once you have your inspection process dialed in, there is still the fund release timeline.
Here is a scenario I see time and time again. You have started the project and things are going well. Then, just as you hit a major milestone, you realize you do not have enough cash to keep things moving. Why? Because the mortgage company is releasing the insurance money in stages.
To make it more complicated, many mortgage companies require the check to be sent to them first. They want to control disbursement of the insurance money to make sure it is used for the restoration work and nothing else. That extra layer of oversight can slow things down dramatically.
Mortgage companies tend to hold back a significant portion of the funding until specific milestones are hit, which creates serious cash flow headaches. The best way to manage it is to understand the stages and build a project timeline that allows for the delays. Here are the standard steps in a mortgage company insurance check release:
| Stage | What gets released | What to have ready |
|---|---|---|
| Initial disbursement | A small percentage of the total claim up front, which can be 20 to 50% of the project | A signed contract and an approved estimate |
| Progress payments | More funds as you hit milestones, such as completing structural work or passing inspections | Photos, detailed invoices and progress reports, plus a passed inspection |
| Final payment | The bulk of the money, after the project is 100% complete | Everything needed to pass a comprehensive final inspection |
Initial disbursement. Mortgage companies typically release a small percentage of the total claim up front. It can be 20 to 50% of the total project, but do not build a timeline that assumes you will get the full 50%. You are setting yourself up for frustration.
Tip: No inspection is usually required for this first payment, so move quickly on signing the contract and submitting an approved estimate. Those are the steps standing between you and getting paid.
Progress payments. As you hit key milestones, like completing structural work or passing inspections, more funds are released. Until those inspections are done, you wait.

Tip: Progress payments often follow specific work phases (for example demolition or framing) or a percentage of completion (for example 50% or 75%). Along with passing an inspection, you may need photos, detailed invoices or progress reports.
Call ahead to understand the expectations and prepare your paperwork. Having every document ready on inspection day speeds up your payment considerably.
Final payment. The final disbursement, the one that holds the bulk of the money, only comes after the project is 100% complete and passes all inspections.
Tip: A comprehensive inspection is required at this stage. Call ahead to understand its scope so you are fully prepared and can clear the final milestone without hurdles.
When you build your timeline, account for these delays and funding milestones. Do not count on having the cash before you pass them. Build a budget and a process that is both strategic and realistic. For a full system around follow-up and escalation, see our guide to building a restoration collections process.
You already know the mortgage company is going to delay payments, so plan for it. Managing cash flow well is what keeps operations smooth when payments are slow.

Restoration checks often require not one but two signatures before they can be cashed or deposited: one from the homeowner and one from the mortgage company. Just when you are ready to wrap up a project, you are stuck waiting.
A check signed by the homeowner alone is not enough. Until the insurance check is endorsed by the mortgage company too, nobody can deposit it. On jobs where the carrier, the adjuster and the homeowner are all in the mix, our guide to how restoration contractors collect from carriers, adjusters and homeowners maps who to follow up with and when. This can add days, weeks or even months. It is not anyone's fault and it is not changeable. It is simply time you must build into your understanding of the project.
Mortgage companies love paperwork, and every disbursement requires a lot of it. Miss a single detail and your payment is delayed further. You do not have to drown in admin work, though.
Standardized templates: Create templates for invoices, receipts and progress reports that meet the requirements of every mortgage company you work with. That streamlines the process, saves time on the project, and makes it easier to gather and submit what is needed.
Chasing a mortgage company job means dozens of small touches: a reminder to the homeowner to call the lender, a note that an inspection is due, a nudge when a draw has been approved but not paid. None of that needs to depend on someone remembering. Automated payment reminders handle the routine follow-up so your office can focus on the files that need a person.
Automate the process: Software can generate invoices, track project progress, and manage and submit your documentation. The more you automate, the less time you spend on paperwork. The more organized the project, the faster you get paid.

Roof replacements are often a single phase, so many lenders release roofing funds in one or two draws. Ask whether the lender will inspect from photos or needs an on-site visit, and take dated photos of the tear-off, decking and finished roof. Our roofing collections page shows how follow-up can run on insurance roofing jobs.
Mitigation work happens before the lender is even involved, and the mitigation invoice is often paid out of the same insurance claim check. Send your mitigation invoice, moisture logs and drying photos to the homeowner right away so they can include them in the first loss draft packet.
Big rebuilds can run through four or more draws. Map each draw to a construction milestone in your contract, so the homeowner, the lender and your crew all know what triggers the next payment. If the homeowner has signed a direction to pay, ask the lender whether it will name you on later checks. Our post on direct insurance billing explains how that works with carriers.
We started out talking about outsmarting mortgage companies, but we encourage you to think of your interactions with them as collaboration.
Mortgage company involvement is not going away. It is shaping the future of the restoration industry. What often feels like a roadblock to payment is also an opportunity to improve business practices for contractors willing to adapt, learn and grow. By requiring compliance with building codes and industry standards, mortgage companies push contractors to deliver higher-quality work, and that is a good thing.

You can absolutely level up your business practices and work well with mortgage companies using the tools you already have. We built a tool to make much of the above simpler.
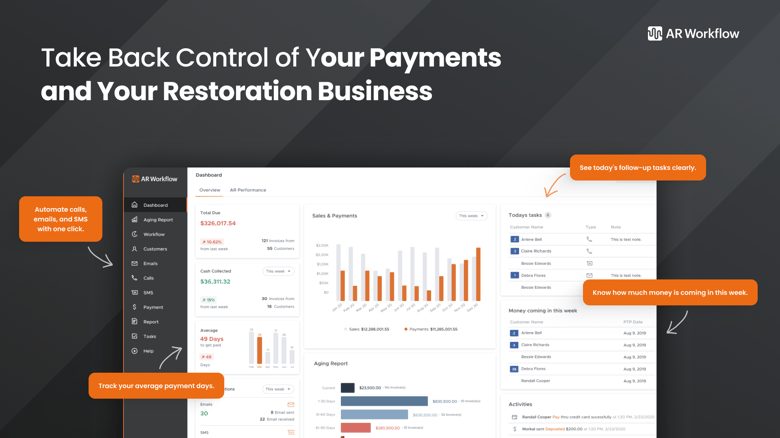
AR Workflow for restoration businesses helps you automate your follow-ups, standardize your communication and keep your documentation in one place. Emails and texts go out on schedule, with texts and voicemails sent from a dedicated number, and it connects with QuickBooks. If you are on QuickBooks Online, our QuickBooks accounts receivable automation guide explains how that works.

Collection workflows decide when each follow-up goes out.

The aging report shows which balances are waiting on which stage.
When a property has a mortgage, the lender has a financial interest in it. The insurance check is usually made out to the homeowner and the mortgage company, and the lender holds or controls the funds to make sure the money is used to restore the property it is protecting.
Call the lender's loss draft department and ask for its release requirements in writing. Most ask for the endorsed check, the adjuster's estimate and a signed contract with the contractor, and some also want a W-9 or lien waivers. Larger claims are usually paid in stages after inspections. Send complete paperwork the first time and follow up every few days.
There is no single limit. It depends on the loan, the lender's rules, state law and the size of the claim. A smaller check may be endorsed and released within days, while larger claims are often held and paid out in stages as work passes inspection, which can stretch across the whole job. Ask the lender for its expected timeline up front.
It is the team at a mortgage servicer that handles insurance claim checks on properties it holds a loan on. It endorses checks, holds larger claims in a loss draft account, schedules inspections and releases funds in stages. The homeowner usually has to start the process, so get the department's contact details early.
Both parties have to endorse it before it can be deposited. The homeowner signs and sends it to the loss draft department, which either endorses and returns it or deposits it and releases the money in draws. This is the most common reason a mortgage company is holding an insurance check on a restoration job.
Ask about inspection and paperwork requirements at the start, document the job every day, have everything ready on inspection day, and send the mortgage company progress updates every few days. For the insurance side of the job, see our guide to speeding up payments from insurance adjusters.
Mortgage companies may be shaping the future of restoration payments, but you do not have to be at their mercy. By understanding their processes, building strong relationships, streamlining your operations and managing your cash flow, you can take back control of your payments and your business.
This is your business. Rise above the challenges, take control of the process, and make room to grow.

Related reading
Your invoice, not a feature tour.
Bring one overdue invoice to a demo and see what AR Workflow would send, when, and to whom.
Sam owned and ran three restoration companies for more than 14 years and collected over $100 million in receivables. He built AR Workflow in 2020 to give contractors the collections system he wished he'd had.

AI writes the emails, sends the texts, and leaves the voicemails. Your team handles the conversations that matter, and your cash keeps moving.
 Keep QuickBooksStart with one invoiceStay in control

 Log in